

EB-5 vs the Trump Gold Card: two US investment green card routes

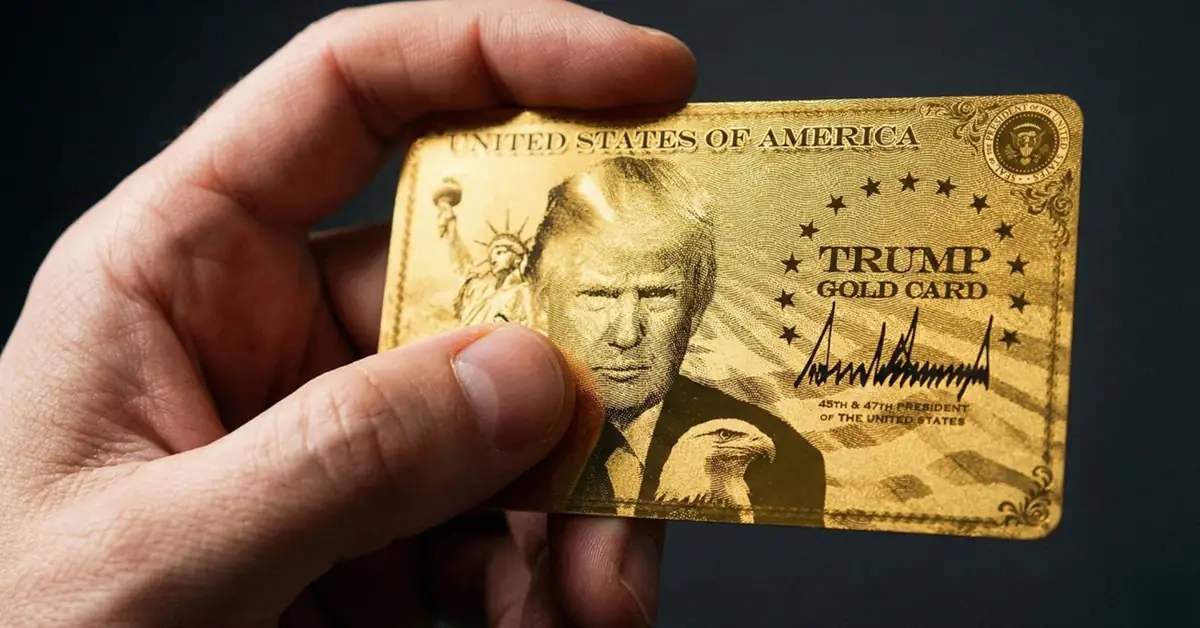
Comparing EB-5 and the Trump Gold Card has become a hot topic for international investors since the Gold Card programme officially opened for applications on 18/12/2025. Both programmes aim to grant green cards to foreign investors, but they differ completely in design philosophy, capital thresholds, process and legal risk.
Visa EB-5is a programme with more than 35 years of history, enacted by the US Congress in 1990 and reformed by the EB-5 Reform and Integrity Act 2022. The Trump Gold Card, meanwhile, is a new programme established by President Donald Trump through Executive Order 14351, signed on 19/09/2025, and currently faces a federal lawsuit over its constitutionality.
This article analyses in detail the differences between the two programmes so investors have a basis for making a decision that fits their financial profile, settlement goals and tolerance for legal risk.
Message
Overview of the two programmes
EB-5 — the traditional immigrant investor programme
EB-5 is a visa programme for foreign investors in the Employment-Based Fifth Preference category. It requires investors to put capital into a business in the United States and create at least 10 full-time jobs for US workers.
According to U.S. Citizenship and Immigration Services (USCIS), EB-5 currently has two investment levels: $1,050,000 USD for standard projects and $800,000 USD for projects in a Targeted Employment Area (TEA). The global visa quota is about 10,000 a year, of which 32% is set aside for three Reserved Visa groups: Rural, High Unemployment and Infrastructure.
EB-5 investors go through two main filing steps: the I-526E (for petitions through a Regional Center) or the I-526 (direct investment), followed by the I-829 to remove the conditions on the green card after 2 years.
The Trump Gold Card — a new programme created by Executive Order
The Trump Gold Card was established by Executive Order 14351 of 19/09/2025 and opened for applications on 18/12/2025. The programme requires investors to make a contribution of $1,000,000 USD (individual) or $2,000,000 USD (a business sponsoring an employee) to the US Department of Commerce, plus a non-refundable $15,000 USD processing fee.
Unlike EB-5, the $1,000,000 USD under the Trump Gold Card is classified as a gift to the federal government, not an investment with the potential for returns. The money cannot be recovered and generates no return for the investor.
Technically, the Trump Gold Card does not create a new visa category but uses the quotas of two existing visa groups,EB-1(Extraordinary Ability) andEB-2(Exceptional Ability/National Interest Waiver). USCIS treats the $1,000,000 USD gift as prima facie evidence that the investor brings significant benefit to the United States.
Considering a residency programme? The Prosperous Living Investment team assesses your profile free of charge and advises on the pathway that fits your goals.
Comparing investment thresholds and costs
| Criterion | EB-5 | Trump Gold Card |
|---|---|---|
| Capital required | $800,000 USD (TEA) or $1,050,000 USD (outside a TEA) | $1,000,000 USD (individual) / $2,000,000 USD (corporate) |
| Nature of the money | A recoverable investment | A non-refundable gift |
| Government processing fees | I-526E about $11,160 USD; I-829 about $9,525 USD | $15,000 USD per person (including spouse and children) |
| Job creation requirement | 10 full-time jobs per investor | None |
| Ability to recover capital | Yes (once the project completes its cycle) | No |
In pure cost terms, EB-5 lets investors recover their capital once the project ends, so the $800,000 USD is not a sunk cost but an at-risk investment. The Trump Gold Card’s $1,000,000 USD, by contrast, is money transferred to the US government, with no refund mechanism under the terms currently published.
For families with several members, the cost of the Trump Gold Card can rise significantly. According to the programme’s official website, each family member (spouse and children under 21) must pay the $15,000 USD processing fee and an additional $1,000,000 USD gift — completely different from EB-5, where the whole family is included in a single petition with the same investment.
Comparing process and processing times
EB-5 follows a clear three-stage process: filing the I-526E (or I-526) for USCIS to approve the project and source of funds; applying for an immigrant visa at a consulate or adjusting status in the United States to receive a conditional green card; and finally filing the I-829 after 2 years to move to aUS permanent resident card.
Overall EB-5 processing usually takes 3 to 7 years depending on the case and the backlog for the applicant’s country. For Vietnamese cases, the priority date often lags 1–2 years behind the date USCIS approves the I-526E because of per-country quotas.
The Trump Gold Card is presented as an expedited adjudication process. The main steps are: applying online with the $15,000 USD processing fee; national security vetting by the Department of Homeland Security (DHS); transferring the $1,000,000 USD gift after passing vetting; approval of Form I-140G; and immigrant visa processing at a consulate through Form DS-260G.
However, although the process is billed as “expedited”, the programme must still comply with the annual quotas and per-country limits of the EB-1 and EB-2 groups. According to theUS Department of State’s Bureau of Consular Affairs, some countries may face wait times of 1 year or more depending on visa availability.
Notably, as of Commerce Secretary Howard Lutnick’s hearing before Congress on 23/04/2026, the programme had approved only 1 application since its launch in December 2025. This figure shows that actual processing is slower than initially expected.
Comparing legal and documentation requirements
EB-5 requirements
EB-5 requires investors to prove two core groups of criteria: a lawful source of funds (SOF) and job creation. Proving source of funds for Vietnamese investors is a complex process, involving tracing the flow of money from income, business, inheritance or assets, with tax documents, accounting records and related contracts over many years.
The requirement to create at least 10 full-time jobs is calculated using Direct Jobs (direct investment) or Indirect/Induced Jobs (through a Regional Center and economic modelling). The jobs must be sustained and fully proven at the time of filing the I-829.
Trump Gold Card requirements
The Trump Gold Card’s legal requirements are simpler in quantitative terms but complex in terms of their underlying legal basis. Applicants must prove they have not committed crimes of moral turpitude, are admissible to DHS on entry and pass national security vetting.
The programme does not require source of funds to be proven to the EB-5 standard, job creation, a business plan or a sustained investment. On paper, it has a significantly lower documentation barrier than EB-5.
However, because it uses the EB-1 and EB-2 quotas, Trump Gold Card applications still have to go through filing the I-140G and DS-260G under the standard process for these two visa groups.
Legal risk — the core difference
This is the difference investors should weigh most carefully when comparing EB-5 and the Trump Gold Card.
EB-5 is a programme established by the US Congress through the Immigration Act of 1990 and reaffirmed and reformed by the EB-5 Reform and Integrity Act of 2022. Its legal basis is a federal statute, which is highly stable and has been extended and amended many times across several administrations.
The Trump Gold Card was created entirely through executive power via Executive Order 14351, without any act of Congress. On 03/02/2026, the American Association of University Professors (AAUP), together with several researchers and immigration experts, filed a federal lawsuit (AAUP v. DHS, Case No. 1:26-cv-00300, D.D.C.) challenging the programme’s legality.
The lawsuit argues that the Gold Card programme violates the Administrative Procedure Act and the Immigration and Nationality Act, and exceeds the executive branch’s constitutional authority. Article I, Section 8 of the US Constitution gives Congress exclusive authority to establish rules of naturalisation, including creating new visa categories.
The plaintiffs argue that taking the EB-1 and EB-2 quotas — categories Congress designed for people with extraordinary ability and for the national interest — and using them for paid applications changes the function of those visa categories without legislative authority.
The District of Columbia court is currently considering the lawsuit. If the court rules against the programme, Gold Card applications already filed could face the risk of being invalidated or suspended. Under the terms currently published on the official website, the contribution is non-refundable, and there is no official mechanism for refunding applicants if the programme is suspended by the courts.
For investors committing several million USD who need a high degree of legal certainty, this is a significant drawback of the Trump Gold Card compared with EB-5.
EB-5 vs the Trump Gold Card on the path to citizenship
Both programmes lead to a permanent resident green card and then to US citizenship.
With EB-5, the investor receives a 2-year conditional green card after the I-526E is approved and the visa is issued. After 2 years, they file the I-829 to remove the conditions and receive a 10-year permanent green card. After a total of 5 years as a permanent resident, the applicant is eligible to file the N-400 for naturalisation.
With the Trump Gold Card, the applicant receives a permanent green card as soon as the visa is issued at the consulate, without a conditional green card stage. The path to citizenship generally also requires 5 years of permanent residence before filing the N-400, as for other permanent resident categories.
In theory, the Trump Gold Card saves 2 years compared with EB-5 in the early stage by skipping the I-829 step. However, the actual timeline still depends on backlogs and the legal risk mentioned above.
The Trump Platinum Card — the $5,000,000 USD version
Investors with larger budgets should also know about the Trump Platinum Card — an additional programme announced on the official website but not yet launched. According to the initial announcement, the Platinum Card will require a contribution of $5,000,000 USD and allow residence in the United States for up to 270 days a year without triggering the Substantial Presence Test, meaning holders would not become tax residents or be taxed on income from outside the United States.
However, the Platinum Card is not included in Executive Order 14351 and currently exists only as a waitlist. Many immigration lawyers have warned about the legal feasibility of the Platinum Card, especially regarding changes to federal tax rules — which fall within the legislative authority of Congress.
For investors considering the Platinum Card, the legal risk is much higher than for the Gold Card, because the programme has no specific executive order, no official forms, and its tax provisions touch on Congress’s authority over the Internal Revenue Code.
Which option suits Vietnamese investors?
Comparing EB-5 and the Trump Gold Card has no default answer; it depends on each investor’s specific profile. EB-5 suits investors who need a high degree of legal certainty, can afford to wait and want to preserve their capital — since the investment can be recovered once the project completes its cycle.
The Trump Gold Card suits investors with large budgets who prioritise speed, do not need to recover their capital and accept the legal risk of a programme being challenged in federal court. The documentation requirements are simpler, but the net (non-refundable) cost is significantly higher, especially for large families.
One factor that is often overlooked is tax. Both programmes make the investor a US permanent resident, which means paying tax on worldwide income after receiving the green card. Tax planning before becoming a tax resident is an important step in optimising the asset structure, for both EB-5 and the Trump Gold Card.
Summary
The arrival of the Trump Gold Card in December 2025 changed the landscape of US immigrant investment, giving investors with large budgets a new option with simple documentation requirements and faster processing. However, the programme currently faces a federal lawsuit over its constitutionality and had approved only a handful of applications as of Q2 2026.
EB-5 remains the only US immigrant investment programme whose legal basis is an act of Congress, proven over more than 35 years of operation and comprehensively reformed in 2022. For most Vietnamese investors, EB-5 remains the safer choice in terms of both capital recovery and legal certainty.
PLI’s team of immigration specialists recommends that investors fully weigh three factors before deciding: their actual budget and ability to absorb a capital loss, their tolerance for legal risk, and a timeline that fits the family’s plans. Consulting a US-licensed immigration lawyer and an international tax adviser is an essential step before committing a large sum to any programme.
Accompanying you on your journey in residency investment
The Prosperous Living Investment team advises on pathways, assesses profiles and manages investments transparently for every residency, citizenship and international property objective.
Free profile assessmentWhere life gets prosperous